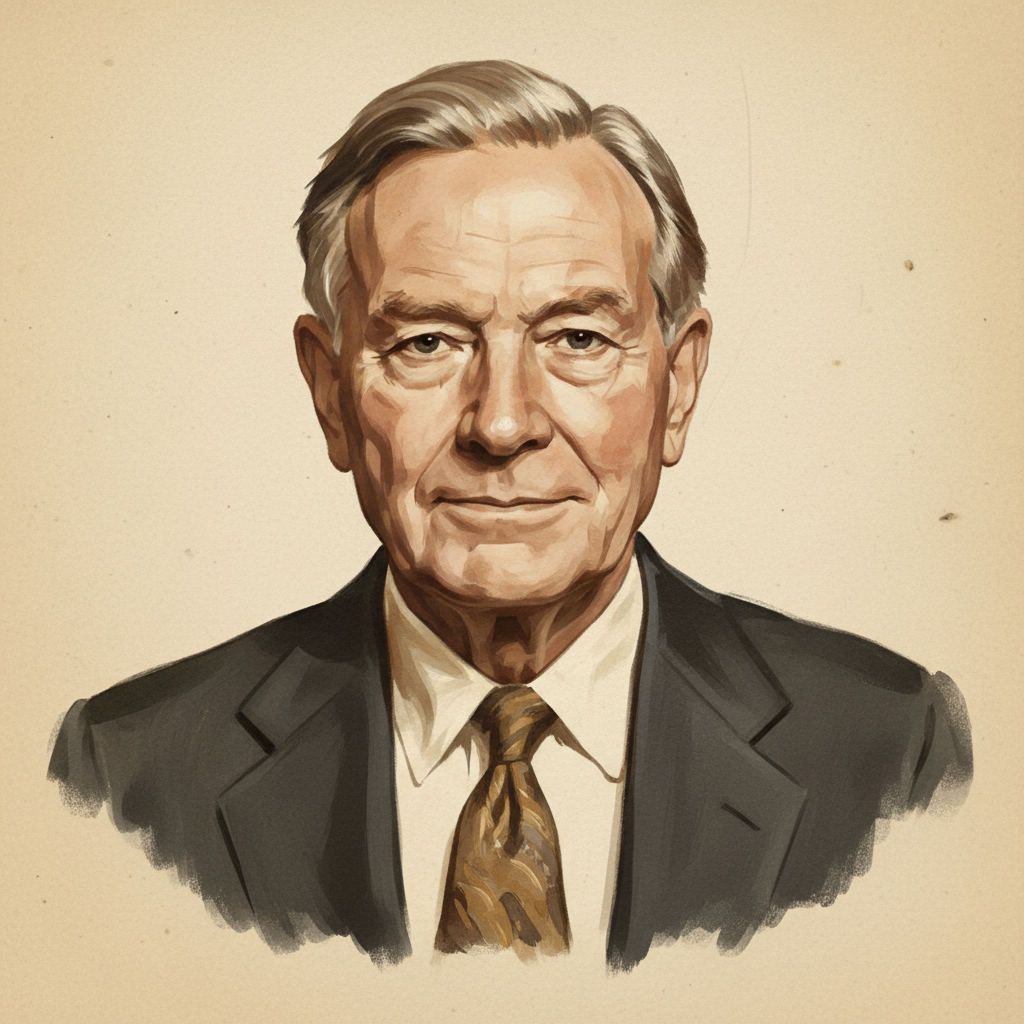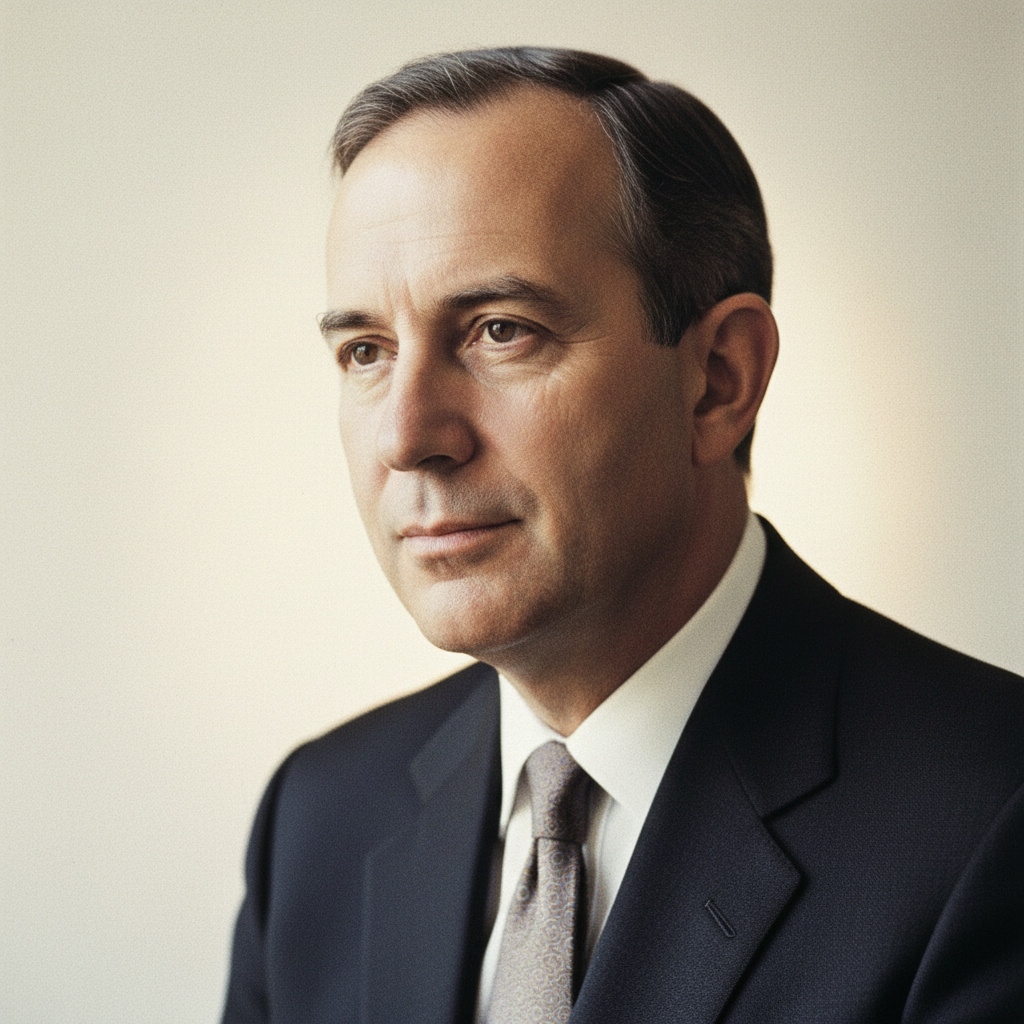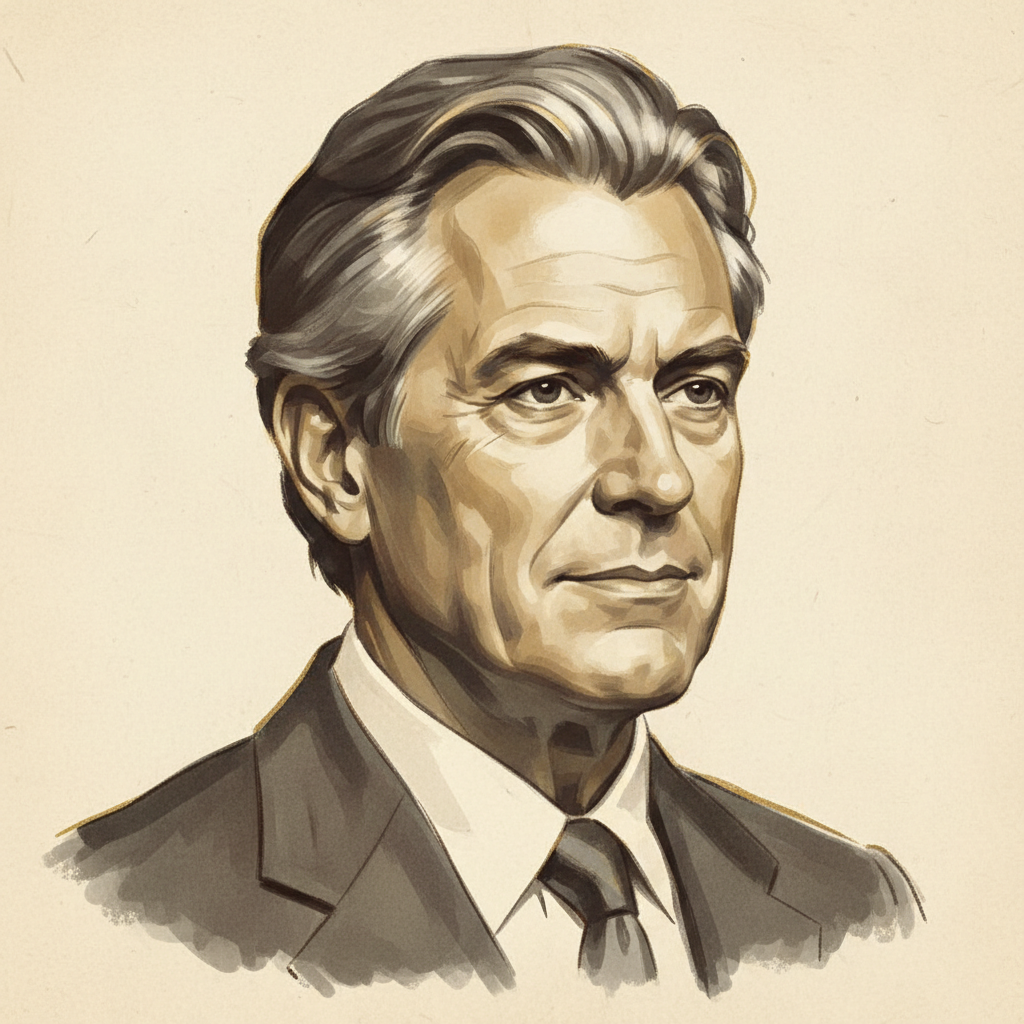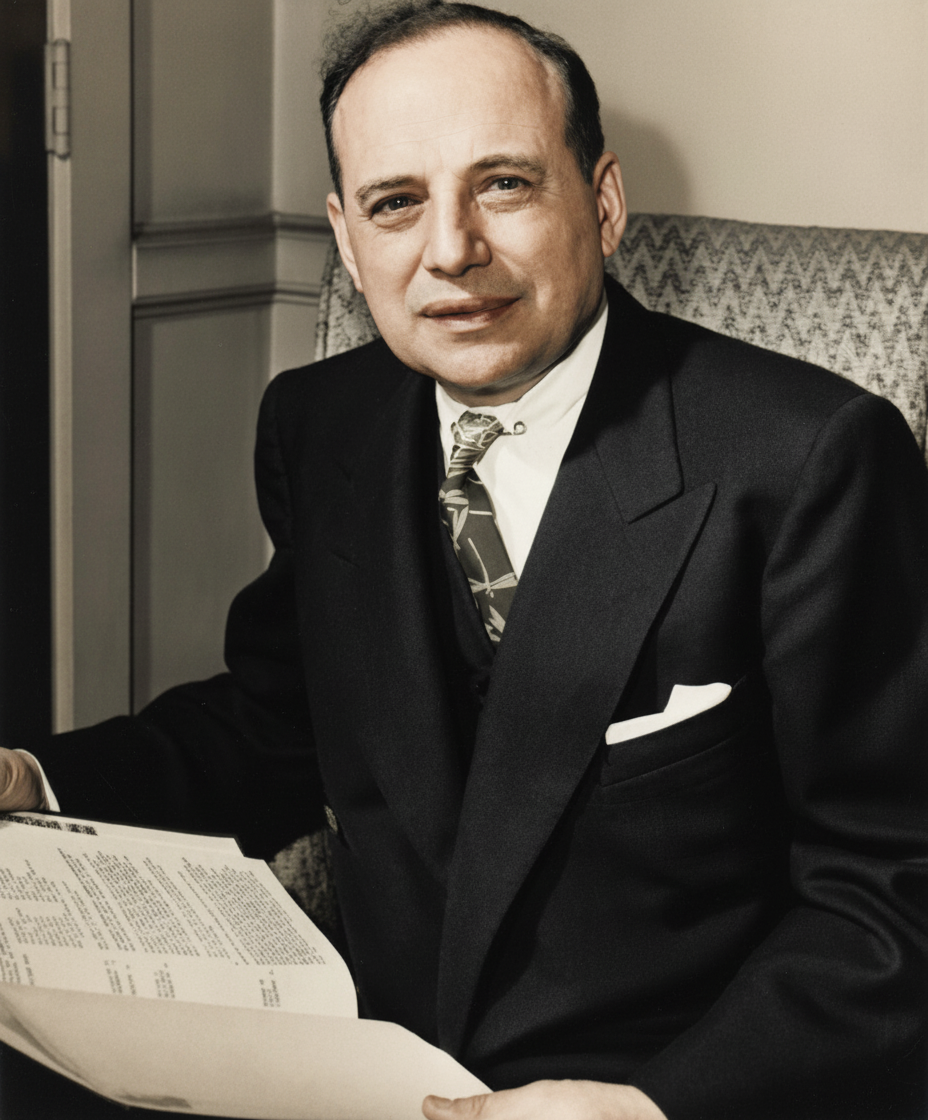
Portrait of Benjamin Graham
Historical Mind · 1894 — 1976

Benjamin Graham

The intellectual architect of value investing, Benjamin Graham codified principles that prioritize intrinsic value over market sentiment.

Country
United States
Continent
North America
Industry
Finance
Role
Investor, Economist, Educator, Author

Benjamin Graham (1894-1976) was an American economist, professor, and investor, widely regarded as the 'Father of Value Investing.' His seminal works, 'Security Analysis' (with David L. Dodd) and 'The Intelligent Investor,' introduced rigorous analytical methods for assessing securities, emphasizing fundamental analysis, the concept of intrinsic value, and capital preservation. Graham's teachings profoundly influenced generations of investors, most notably Warren Buffett, and established a disciplined approach to stock market participation that endures today.

Biography

Born Benjamin Grossbaum in London in 1894, he immigrated to the United States with his family at age one, later changing his surname to Graham during World War I. He graduated as salutatorian from Columbia University in 1914, receiving offers to teach but opting for a career on Wall Street. Graham began as a bond runner, quickly progressing to analyst, and by 1920, was a partner in a brokerage firm. In 1926, he co-founded the Graham-Newman Partnership with Jerome Newman, an investment firm that practiced the principles he later espoused. The firm maintained an impressive track record, averaging returns of about 20% per year for its investors from 1926 until its dissolution in 1956, significantly outperforming the broader market. Graham's investment philosophy was deeply shaped by the market crash of 1929 and the subsequent Great Depression, experiences that underscored the imperative for caution, thorough analysis, and a margin of safety. He served on the faculty of Columbia Business School from 1928 to 1956, where he taught finance and investment management, developing much of the material that would form the basis of 'Security Analysis' (1934). This book, co-authored with David L. Dodd, became the foundational text for fundamental securities analysis. His later work, 'The Intelligent Investor' (1949), served as a more accessible guide for the general public, advocating for a defensive, long-term approach to investing. Graham's influence extended through his students, particularly Warren Buffett, who credits Graham as the single greatest influence on his investment philosophy. Buffett worked for Graham-Newman from 1954 to 1956. Graham's principles emphasized treating stock ownership as owning a part of a business, analyzing financial statements meticulously, seeking a 'margin of safety' by buying assets for significantly less than their intrinsic value, and viewing market fluctuations as opportunities rather than threats. He retired from active money management in 1956, continuing to write and consult until his death in 1976.

Accomplishments

  • 01Co-authored 'Security Analysis' (1934) with David L. Dodd, establishing the academic and practical framework for modern fundamental securities analysis.
  • 02Authored 'The Intelligent Investor' (1949), a foundational text that popularized value investing principles for a broader audience.
  • 03Co-founded and managed the Graham-Newman Partnership (1926-1956), which generated an average annual return of approximately 20%, significantly outperforming the Dow Jones Industrial Average.
  • 04Mentored and directly influenced Warren Buffett, widely considered one of the most successful investors of all time, who consistently credits Graham as his primary intellectual guide.
  • 05Introduced and popularized the concept of 'Margin of Safety,' a critical risk-mitigation principle in investment management.
  • 06Developed the concept of 'Mr. Market,' an allegory to illustrate the irrational and emotional nature of the stock market, advising investors to treat market fluctuations as a partner offering either to buy or sell at various prices, not as a guide for intrinsic value.
  • 07Served as a distinguished professor at Columbia Business School for 28 years (1928-1956), disseminating his investment philosophy to thousands of students.

Lessons for Operators

**Treat Stock as Business Ownership**: When purchasing a stock, view it as acquiring a proportional share of a private business. This perspective encourages deep due diligence into the underlying company's economics, management quality, and competitive advantages, rather than merely speculating on stock price movements. For example, before investing in Coca-Cola, analyze its global distribution network and brand equity as if you were buying the entire enterprise.
**Demand a Margin of Safety**: Always buy securities at a price significantly below their calculated intrinsic value. This discount provides a buffer against errors in judgment, unforeseen economic downturns, or business setbacks. For instance, if you estimate a company's true worth to be $100 per share, aim to purchase it for $60 or less, providing a 40% margin of safety.
**Embrace Market Volatility (Mr. Market)**: The market ('Mr. Market') is your servant, not your master. It will periodically offer stocks at irrationally high or low prices due to euphoria or fear. Do not let market sentiment dictate your investment decisions; instead, exploit these fluctuations by buying when prices are irrationally low (below intrinsic value) and selling when they are irrationally high (above intrinsic value). During a market correction, identify fundamentally sound businesses trading at a discount.
**Conduct Thorough Fundamental Analysis**: Rely on detailed financial statement analysis (balance sheets, income statements, cash flow statements) to understand a company's true economic position and earnings power. Focus on quantifiable metrics like earnings, book value, debt levels, and dividend history rather than ephemeral narratives or growth projections. Before investing, calculate key ratios and project cash flows based on conservative assumptions.
**Invest, Don't Speculate**: Differentiate between investment (based on thorough analysis, promising safety of principal, and adequate return) and speculation (based on price movements or unproven narratives). Maintain a long-term horizon, focusing on the underlying business value. Avoid chasing 'hot' stocks or market fads; instead, build a portfolio of undervalued companies with strong balance sheets and consistent earnings.
**Maintain Emotional Discipline**: Investor success is as much about temperament as intellect. Resist the urge to panic during market downturns or become overly euphoric during upswings. Adhere to your analytical framework regardless of external market noise. For instance, pre-define your buy and sell criteria and stick to them even when the news cycle is negative or overwhelmingly positive.
**Diversify Adequately**: While concentrating investments in deeply undervalued opportunities can be profitable, broad diversification across a reasonable number of securities (e.g., 10-30 companies) helps mitigate the risk of any single investment underperforming or failing entirely. This protects capital while still allowing for significant returns from successful picks.
The Operator's Playbook

Key Takeaways

Practical lessons distilled for operators, investors, C-levels, and capital allocators.

Lesson 01

Intrinsic Value Focus

Graham championed the idea that every security has an underlying intrinsic value, which can be determined through diligent analysis of its assets, earnings, and future prospects, independent of its current market price. Successful investing involves buying when market price is significantly below this intrinsic value.

Lesson 02

Margin of Safety

This core concept dictates buying securities at a substantial discount to their estimated intrinsic worth. It acts as a protective buffer against analytical errors, adverse business developments, or market downturns, preserving capital and enhancing returns.

Lesson 03

Investor vs. Speculator

Graham rigorously distinguished between investing (a disciplined process based on thorough analysis, seeking safety of principal and a satisfactory return) and speculating (gambling on price fluctuations without fundamental justification). He advocated for a clear, analytical approach over emotional trading.

Lesson 04

Mr. Market Allegory

His 'Mr. Market' analogy personifies the stock market as a manic-depressive business partner who daily offers to buy or sell your shares at wildly fluctuating prices. Graham advised treating Mr. Market as a source of opportunities (to buy cheap or sell dear) rather than a source of wisdom.

Lesson 05

Defensive Investing

For general investors, Graham recommended a 'defensive' approach: investing in large, financially strong, diversified companies with a history of stable earnings and dividends, and maintaining a balanced portfolio between stocks and bonds, adjusting based on market conditions.

Lesson 06

Analytical Discipline

Graham's methodology underscored the importance of rigorous, quantitative analysis of financial statements. He taught investors to scrutinize balance sheets, income statements, and cash flows to understand a business's true health and value, rejecting reliance on forecasts or market sentiment.

Mental Models

Frameworks & Principles

Named frameworks and strategic principles they popularized or embodied.

01

Intrinsic Value Calculation

A methodical approach to determine a company's true worth based on its assets, earnings power, dividends, and future prospects, distinct from its market price. Graham emphasized analyzing tangible assets, earnings stability, and debt levels.

When to useWhen evaluating any potential equity investment. Before committing capital, calculate the intrinsic value using conservative assumptions to establish a baseline for your purchase decision. This forms the foundation for applying the margin of safety.

02

Margin of Safety Principle

The practice of purchasing securities only when their market price is significantly below their calculated intrinsic value. This discount provides a cushion against analytical errors, economic downturns, or business specific problems, protecting capital and improving return potential.

When to useApplied universally to all investment decisions. Once an intrinsic value is estimated, establish a minimum percentage discount (e.g., 30-50%) that the market price must offer before considering a purchase. This is crucial for risk management and long-term wealth creation.

03

Mr. Market Exploitation

Utilizing the market's irrational fluctuations as opportunities. Instead of being swayed by market sentiment, an investor should view 'Mr. Market' as a business partner who periodically offers to buy or sell at illogical prices. One buys when prices are irrationally low and sells when they are irrationally high.

When to useDuring periods of market volatility, significant downturns (bear markets), or irrational exuberance (bull markets). Instead of panicking during crashes or getting caught up in speculative bubbles, use these times to identify mispriced assets relative to their intrinsic value.

04

Defensive Investor Portfolio Construction

A strategy for individual investors emphasizing capital preservation and reasonable returns through diversified holdings of large, financially strong companies with stable earnings and long dividend histories. It typically involves a balanced portfolio of high-grade bonds and common stocks.

When to useFor investors seeking a steady, low-stress approach to wealth accumulation, particularly those who lack the time or expertise for intensive research. This framework is suitable for long-term investors prioritizing stability and consistent returns over speculative growth.

Citations

Sources & Further Reading

Profiles, interviews, podcasts, and articles used to compile and verify this entry. Each link opens at the original publisher.

Adjacent Minds

Explore Related Titans

Other figures in the archive who share Benjamin Graham's domain, geography, or era.

Finance & Investing

More in Finance & Investing

Browse all →
Portrait of Warren Buffett
UNITED STATES / INVESTING
Warren Buffett
The Oracle of Omaha: Architect of long-term value investing and compounding returns through disciplined acquisition and intrinsic value focus.
Portrait of Charlie Munger
USA / DIVERSIFIED HOLDINGS, INVESTMENT MANAGEMENT
Charlie Munger
The architect of modern value investing at Berkshire Hathaway, known for his multidisciplinary approach and acerbic wit.
Portrait of Mohnish Pabrai
UNITED STATES / FINANCIAL SERVICES
Mohnish Pabrai
The Dhandho Investor: A Value Investing Maverick.
Portrait of Ray Dalio
UNITED STATES / INVESTMENT MANAGEMENT
Ray Dalio
The architect of 'radical transparency' and systematic investing, Ray Dalio built Bridgewater Associates into one of the world's largest and most influential hedge funds.
Portrait of Sam Altman
UNITED STATES / ARTIFICIAL INTELLIGENCE, VENTURE CAPITAL
Sam Altman
Architect of Artificial General Intelligence and Venture Capital Visionary.
Portrait of J. Pierpont Morgan
UNITED STATES / BANKING & FINANCE
J. Pierpont Morgan
The architect of American industrial capitalism and financial stability.
Portrait of Cosimo de' Medici
ITALY / BANKING, FINANCE, STATESMANSHIP
Cosimo de' Medici
The architect of Medici power, leveraging finance and cultural patronage to establish a dynastic legacy.
Portrait of Giovanni di Bicci de' Medici
ITALY / BANKING AND FINANCE
Giovanni di Bicci de' Medici
The silent architect of Florence's financial supremacy and the Medici dynasty.
Portrait of Jerome Powell
UNITED STATES / CENTRAL BANKING, PUBLIC SERVICE
Jerome Powell
The Maestro of Monetary Policy: Navigating Economic Headwinds and Shaping the Federal Reserve's Modern Era
Portrait of Bruce Kovner
UNITED STATES / FINANCIAL SERVICES
Bruce Kovner
Pioneering Macro Trader and Founder of Caxton Associates
United States

From United States

Browse all →
Portrait of Andrew Carnegie
UNITED STATES / STEEL & MANUFACTURING
Andrew Carnegie
The architect of American steel supremacy and a pioneering industrialist whose innovations in cost control and vertical integration reshaped global manufacturing.
Portrait of Warren Buffett
UNITED STATES / INVESTING
Warren Buffett
The Oracle of Omaha: Architect of long-term value investing and compounding returns through disciplined acquisition and intrinsic value focus.
Portrait of Jeff Bezos
UNITED STATES / TECHNOLOGY, RETAIL, LOGISTICS, CLOUD COMPUTING, SPACE EXPLORATION
Jeff Bezos
Architect of Amazon, pioneer of e-commerce, and visionary across cloud computing, logistics, and space exploration.
Portrait of Bill Gates
UNITED STATES / SOFTWARE, TECHNOLOGY, PHILANTHROPY
Bill Gates
Co-founder of Microsoft, architect of the personal computing revolution, and global philanthropist.
Portrait of Sam Walton
UNITED STATES / RETAIL
Sam Walton
The architect of modern retail, pioneering discount merchandising and logistical efficiency to establish the world's largest retail corporation.
Portrait of Mark Cuban
UNITED STATES / TECHNOLOGY, MEDIA, SPORTS, HEALTHCARE
Mark Cuban
Mark Cuban: The Prolific Disrupter – From Software Startups to Sports Franchises and Pharmaceutical Innovation, Leveraging Technology and Direct-to-Consumer Models.
Portrait of Henry Ford
UNITED STATES / AUTOMOTIVE
Henry Ford
The architect of mass production, democratizing the automobile through efficiency and scale.
Portrait of Walt Disney
UNITED STATES / ENTERTAINMENT
Walt Disney
Co-founder of The Walt Disney Company, pioneering animation, theme parks, and diversified entertainment.
Portrait of Mohnish Pabrai
UNITED STATES / FINANCIAL SERVICES
Mohnish Pabrai
The Dhandho Investor: A Value Investing Maverick.
Portrait of Ray Dalio
UNITED STATES / INVESTMENT MANAGEMENT
Ray Dalio
The architect of 'radical transparency' and systematic investing, Ray Dalio built Bridgewater Associates into one of the world's largest and most influential hedge funds.