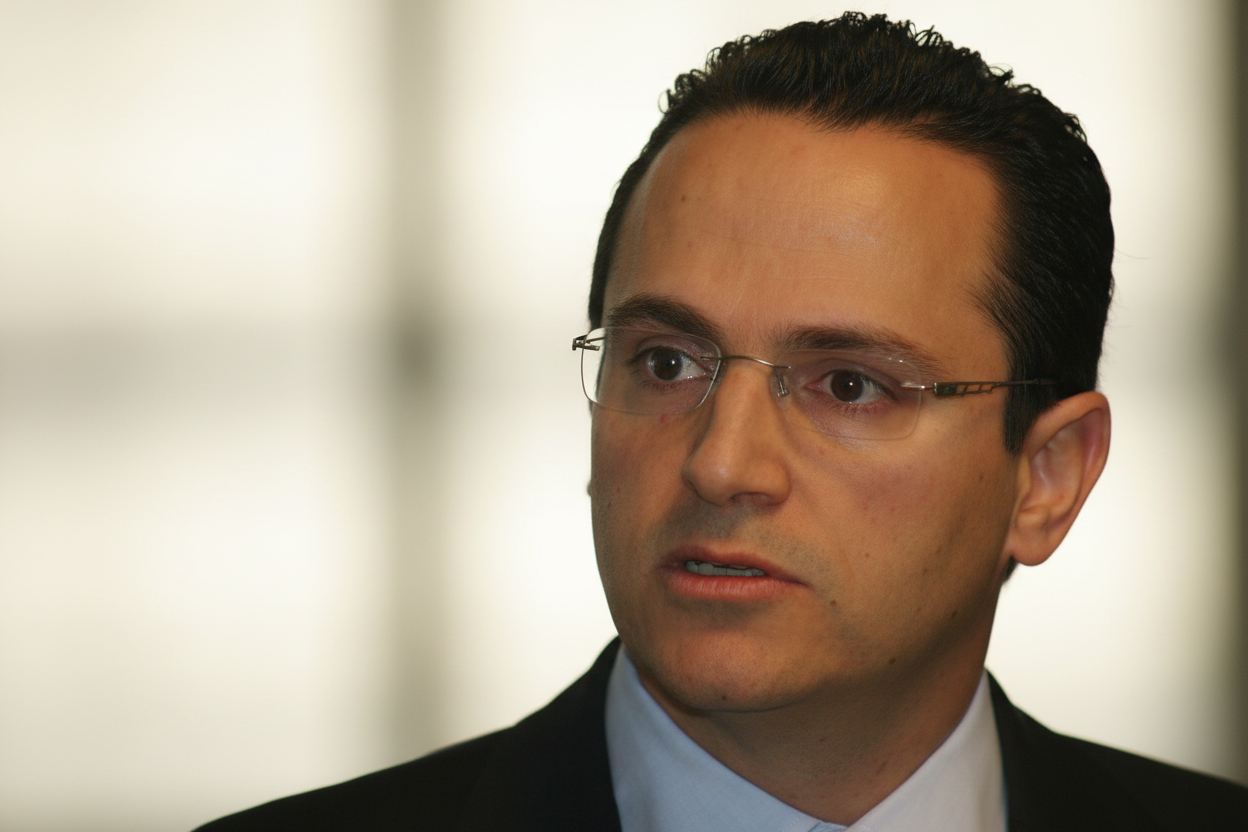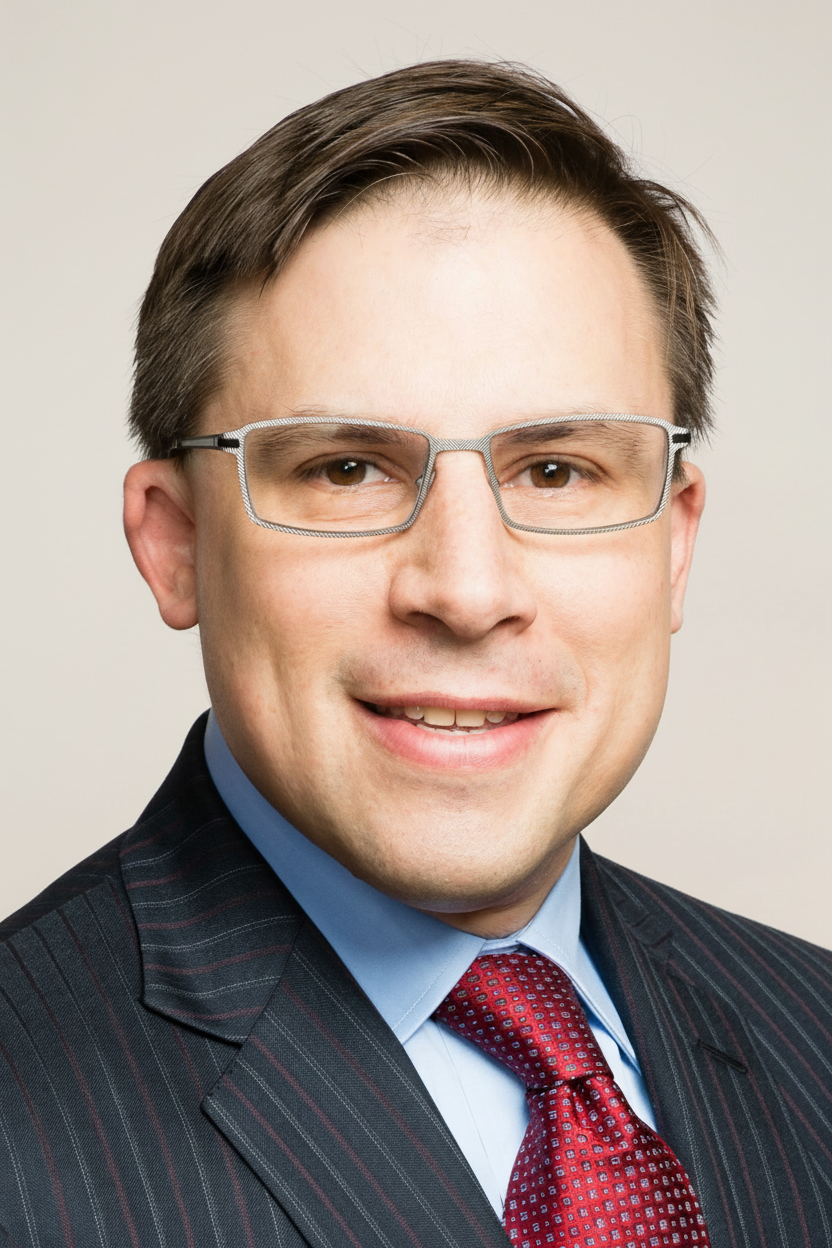
Tobias Moskowitz
A leading financial economist whose empirical research rigorously challenges and refines established investment paradigms, particularly regarding market inefficiencies, momentum, and value strategies.
Tobias J. Moskowitz is an American financial economist and professor known for his influential research in asset pricing, behavioral finance, and empirical market inefficiencies. He holds professorships at the Yale School of Management and previously at the University of Chicago Booth School of Business. Moskowitz was awarded the 2007 American Finance Association Fischer Black Prize for significant contributions to finance by a scholar under 40, and is a principal at AQR Capital Management.
Biography
Accomplishments
- 01Awarded the 2007 American Finance Association (AFA) Fischer Black Prize, recognizing him as a leading finance scholar under the age of 40 for significant contributions.
- 02Authored or co-authored numerous highly cited papers in top academic journals, including 'Momentum in Stock Returns Around the World' (with Cliff Asness and Lasse Pedersen, 2013), 'Time Series Momentum' (with Cliff Asness and Lasse Pedersen, 2013), and 'Fragile Futures' (with Anna Scherbina, 2007).
- 03Developed a robust empirical framework for analyzing momentum and value strategies across various asset classes, demonstrating their persistence and global applicability.
- 04Co-authored 'Man vs. Markets: Securities Trading in an Electronic Age' (with Markus Brunnermeier and Stefan Nagel, 2015), providing insights into high-frequency trading and market microstructure.
- 05Served as a principal at AQR Capital Management, applying academic research to practical, quantitative investment strategies and contributing to portfolio construction and risk management.
- 06Held professorships at two elite institutions: the University of Chicago Booth School of Business and the Yale School of Management, influencing generations of finance students and researchers.
Lessons for Operators
Key Takeaways
Practical lessons distilled for operators, investors, C-levels, and capital allocators.
Factor Investing is King
Moskowitz's research provides compelling evidence that systematic factors like momentum, value, and quality are robust drivers of returns across global markets and asset classes. Operators and investors should identify and consistently allocate to these proven factors rather than attempting to pick individual stocks or time markets, which have poor success rates.
Momentum is Not Just for Stocks
While often associated with equities, Moskowitz's work, particularly 'Time Series Momentum' (2013), demonstrates that momentum strategies (buying past winners, selling past losers) are effective across bonds, commodities, and currencies. Diversifying momentum across asset classes can enhance returns and reduce portfolio volatility.
Challenge the Status Quo with Data
His career exemplifies the value of rigorous empirical testing against prevailing financial theories. Instead of blindly accepting established beliefs (e.g., efficient market hypothesis as a perfect description), investors should continuously scrutinize claims with comprehensive data and statistical analysis.
The Persistence of the Value Premium
Despite periods of underperformance, Moskowitz's research supports the long-term persistence of the value premium – the tendency for undervalued assets to outperform over time. This reinforces the importance of maintaining exposure to value strategies even during challenging cycles.
Avoid Excessive Fees and Complexity
His work often implies that many complex, high-fee active strategies fail to outperform simple, systematic factor-based approaches after costs. C-levels and fund managers should focus on cost-efficient, transparent, and robust investment processes.
Long-Term View is Crucial
Market anomalies and factor premia often manifest over longer horizons. Short-term market noise can obscure underlying factor performance. Adopting a long-term perspective and disciplined execution is essential for capturing these premia.
Frameworks & Principles
Named frameworks and strategic principles they popularized or embodied.
Time Series Momentum
A strategy that exploits the tendency of an asset's past returns to predict its future returns. It involves going long an asset if its own past return was positive and short if negative, often using a lookback period (e.g., 12 months) and a simple moving average or threshold.
When to useApplicable across a broad range of asset classes (stocks, bonds, commodities, currencies) to capture trend-following premia. Useful for tactical asset allocation and diversifying traditional cross-sectional momentum strategies. Ideal for investors seeking systematic trend exposure.
Cross-Sectional Momentum
A strategy that buys assets that have performed well relative to other assets in the recent past (e.g., 3-12 months) and sells assets that have performed poorly. This is distinct from time-series momentum which looks at an asset's past performance against its own history.
When to usePrimarily used within equity markets to sort stocks based on their relative performance. It's a key factor in quantitative equity strategies and can be combined with other factors like value for enhanced returns and diversification.
Factor Investing
An investment approach that targets specific drivers of return (factors) that have been historically shown to earn a risk premium. Common factors include Value, Momentum, Size, Quality, and Low Volatility.
When to useApplicable for constructing diversified portfolios across asset classes, identifying systematic sources of return, and explaining portfolio performance. Operators and investors can use it to build robust, rules-based strategies that capture well-documented risk premia more efficiently than traditional market-cap-weighted indices or individual stock picking.
Value vs. Growth Investing (Empirical Re-evaluation)
Moskowitz's work, often with others, rigorously tests the efficacy and persistence of the 'value' premium (buying cheap assets relative to fundamentals) against 'growth' (buying expensive assets with high expected earnings growth). His research supports the long-term outperformance of value.
When to useEssential for long-term equity investors deciding between value and growth-oriented strategies. It encourages systematic exposure to value stocks, particularly during periods when they are out of favor, based on historical evidence of long-term outperformance. It informs decisions about portfolio tilt and factor exposure.
Recent Appearances
Latest interviews, keynotes, and press from the past half year.
 youtube.com
 youtube.com
 youtube.com
 youtube.com
 youtube.com
 youtube.com
 youtube.com
 youtube.com
Sources & Further Reading
Profiles, interviews, podcasts, and articles used to compile and verify this entry. Each link opens at the original publisher.
Explore Related Titans
Other figures in the archive who share Tobias Moskowitz's domain, geography, or era.
More in Finance & Investing
From United States
Contemporaries — born 1970s